Pymwymic calls for earlier corporate investment in agrifood
The impact investor says corporate venture funds should take more early-stage innovation risk as agrifood startups face a tighter capital market
viernes 25 de septiembre de 2026 - 16:01
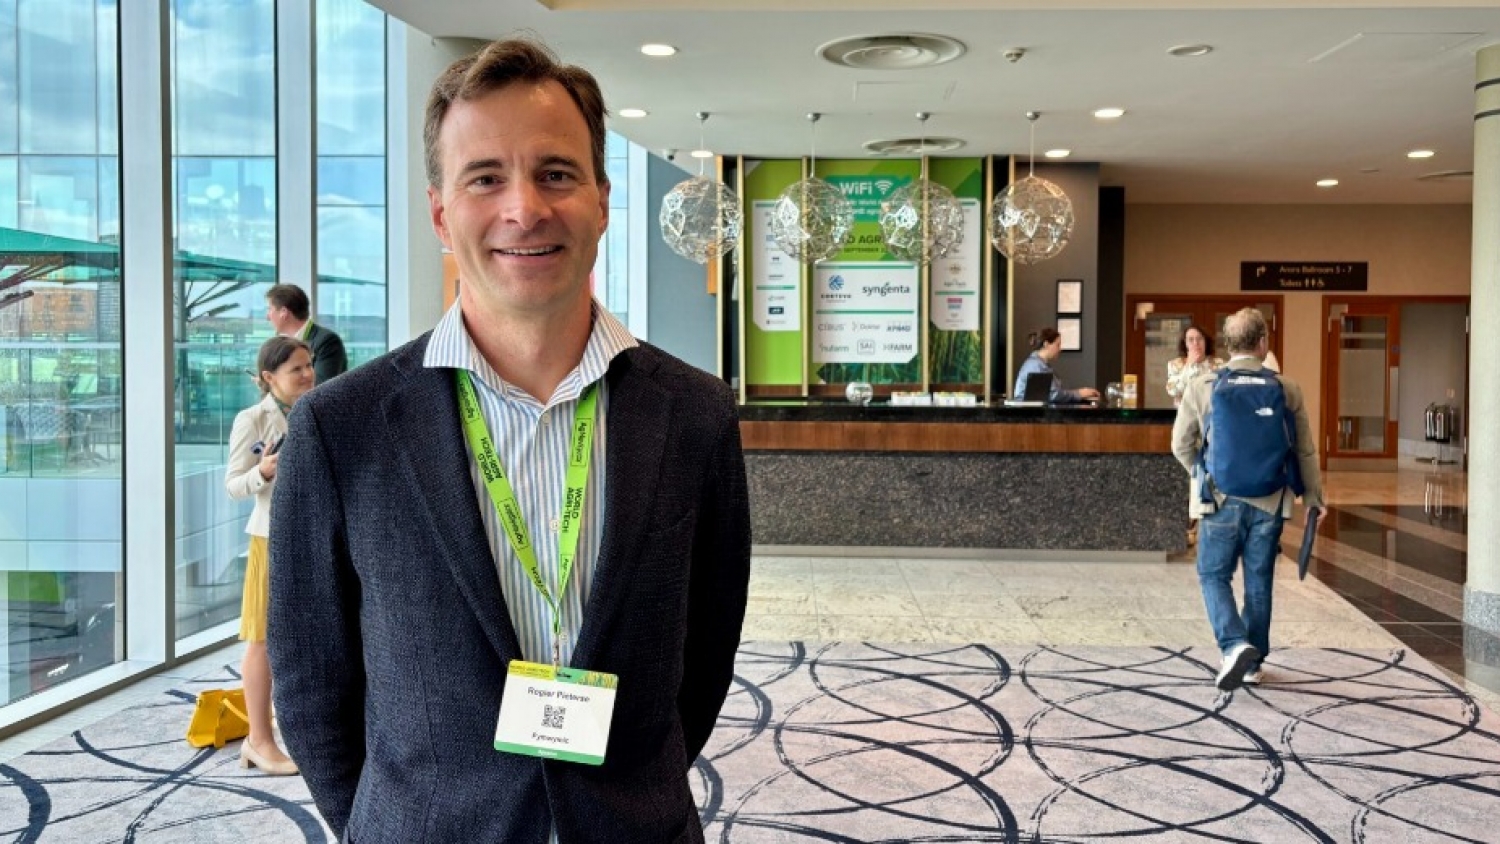
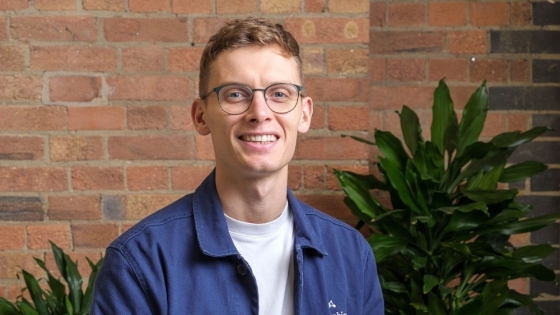
Corporate venture capital should enter agrifoodtech at an earlier stage and take on more innovation risk as startups face a growing funding gap, according to Pymwymic managing partner Rogier Pieterse. Speaking at the World Agri-Tech Innovation Summit in London, Pieterse argued that the sector needs a different investment model, with corporate capital supporting innovation earlier and private equity stepping in later to accelerate growth, according to AgFunderNews.
The proposal reflects a broader challenge for agrifoodtech investment. Less capital is currently available for early-stage and loss-making companies, while many agricultural technologies require longer development and commercialization periods than conventional venture capital models typically accommodate.
Pymwymic is taking a different approach from the traditional Silicon Valley venture capital strategy, which often relies on a small number of portfolio companies generating very large returns to compensate for other investments.
“We don’t believe in what we call the US VC model, where you invest in one or two winners, which are then supposedly going to return your fund,” Pieterse said.
Instead, the investment firm focuses on building a portfolio with more consistent outcomes and fewer failures. Rather than targeting returns of 10 or 100 times the original investment, Pymwymic seeks an average return of around 10%, according to Pieterse.
That strategy faces its own challenges. Institutional investors increasingly expect returns of at least 15%, he said, but Pymwymic maintains that its model has already returned capital to limited partners and remains on track toward the return target promised to investors.
The firm also has the support of Pymwymic Coöperatief, an investment cooperative composed of private investors, families, family foundations and selected individuals.
One of the main concerns is what happens when early-stage agrifood startups need additional capital. Pieterse said the decline in available funding creates opportunities to invest at lower valuations, but also increases uncertainty around follow-on rounds.
To address that issue, Pymwymic added an evergreen growth fund focused on profitable companies. The structure could allow successful businesses from its early-stage portfolio to move into the growth portfolio and remain backed for longer periods.
The strategy reflects the longer timelines often required for agricultural and food technologies to reach scale. Unlike conventional venture funds with fixed end dates, an evergreen structure can provide greater flexibility when companies need additional time to develop.
Pieterse believes corporate venture capital will have to play a larger role in this transition.
“I believe corporate ventures will need to take that innovation risk a bit more, and then private equity growth capital will come in later to accelerate that growth,” he said.
Under that model, corporations would become involved earlier instead of waiting until startups have already passed much of the technological development risk. Pymwymic also wants strategic investors represented on the capitalization tables of its venture investments.
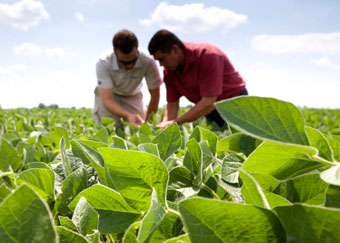
Despite changes in the funding environment, Pieterse said the firm's core investment thesis has remained consistent. Pymwymic prioritizes farmer adoption, unit economics and reasonable entry valuations rather than relying primarily on projections about the theoretical size of future markets.
The company also avoided much of the earlier investment rush into areas such as vertical farming and alternative proteins. However, changing valuations and lessons from the sector led Pymwymic to make its first alternative protein investment last year.
Looking ahead, Pieterse sees opportunities in precision agriculture, precision spraying, nutrient management and regenerative farming. His view is that agricultural systems will increasingly need to use soil and field data to make input decisions more efficiently.
Biological agricultural products are another area expected to develop over time, although Pieterse cautioned that the transition could be gradual, similar to the evolution of renewable energy technologies.
Agricultural robotics is also becoming more investable as standardized components become cheaper and advances in data and artificial intelligence improve machine capabilities. But practical conditions in the field continue to limit fully autonomous operation.
Irrigation lines, obstacles and equipment problems can still require human intervention, which can make it harder for agricultural robots to scale as quickly as technologies operating in more controlled environments.
Artificial intelligence is meanwhile increasing the value of proprietary agricultural datasets. Around 75% to 80% of Pymwymic's portfolio combines hardware, software or data-driven technologies, according to Pieterse.
For these companies, competitive advantage may increasingly depend on the quality and uniqueness of their data. Historical datasets capable of distinguishing specific pests or translating field information into actionable recommendations for farmers can provide a level of differentiation that widely available AI tools cannot necessarily reproduce.
The broader challenge is therefore not only identifying promising agricultural technologies but also developing financing structures capable of supporting them through longer commercialization cycles. Pymwymic's approach points toward a model in which venture capital, corporate investors and private equity participate at different stages, with corporate capital assuming a larger share of the early innovation risk.
Invertí en periodismo de calidad
En Agroempresario trabajamos para acercarte contenidos que agregan valor.